Publications
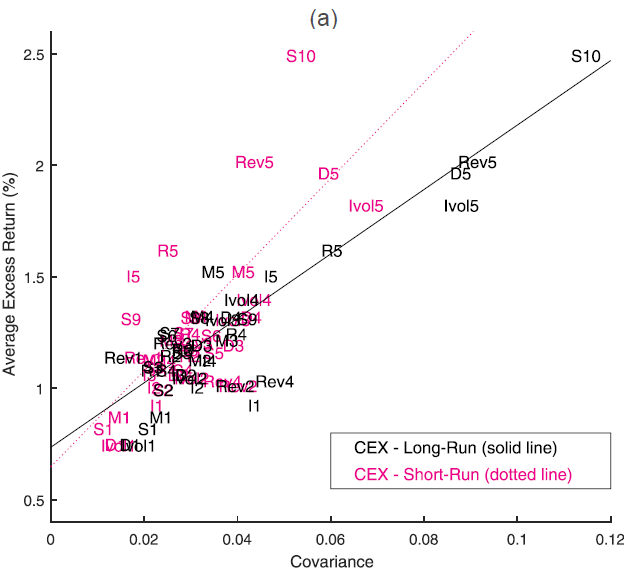
A One-Factor Model of Corporate Bond Premia
with Redouane Elkamhi and Yoshio Nozawa
Management Science, 2024, Data and code, SSRN version, Online Appendix, [+ bibtex]
Empirical asset pricing, Long-run risk, Wealthy households' Consumption
Abstract
A one-factor model based on long-run consumption growth explains the risk premiums on corporate bond portfolios sorted on credit rating, credit spreads, downside risk, idiosyncratic volatility, long-term reversals, maturity, and sensitivity to the financial intermediary capital factor. The estimated risk-aversion coefficient is lower when we use the consumption growth of wealthy households over a longer horizon as a risk factor, and a model with a 20-quarter horizon yields a risk-aversion coefficient of 15, a value similar to the one estimated from equity portfolios.Key result
Measuring "State-level" Economic Policy Uncertainty
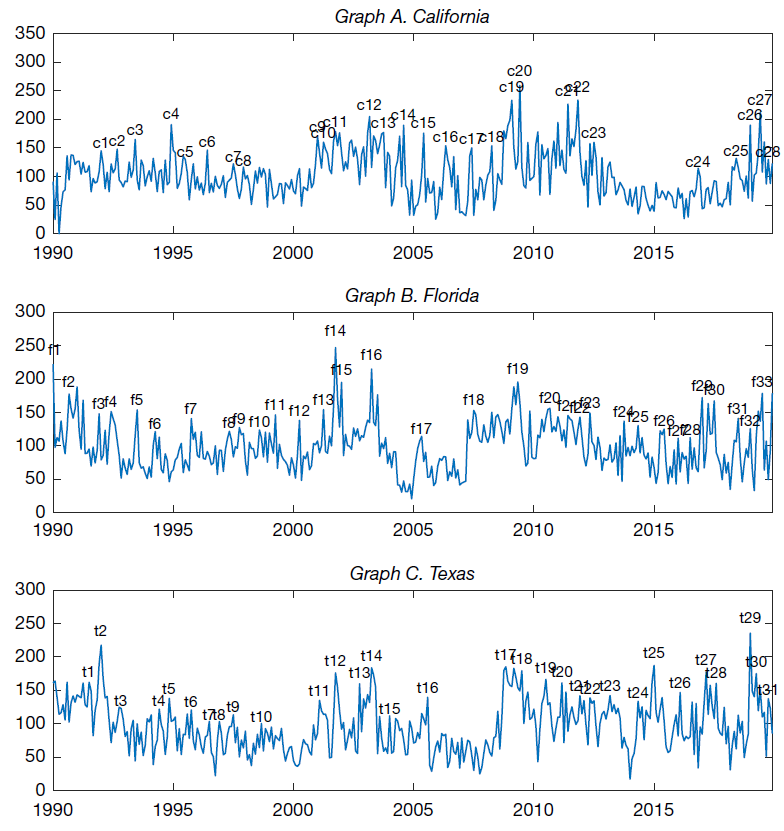
with Redouane Elkamhi and Marco Salerno
Journal of Financial and Quantitative Analysis, 2024, Data, SSRN version, Online Appendix, [+ bibtex]
Measuring state-level economic uncertainty and applications to corporate finance & asset pricing
Abstract
We develop 50 indices of State-level Economic Policy Uncertainty (SEPU) based on newspaper coverage frequency using 204 million newspaper articles from March 1984 to December 2019. We assess the validity of our measures. Our SEPU indices vary counter-cyclically with respect to state-specific economic conditions, rise before close gubernatorial elections, and exhibit a large cross-sectional variation. We demonstrate that SEPU indices are associated with the cross-sectional variation in state-level GDP, employment, income as well as industry investment decisions. Our findings highlight the importance of economic policy uncertainty at the state level in addition to the nationwide level.Key result
Agency Conflicts and Investment: Evidence from a Structural Estimation
with Redouane Elkamhi, Daniel Kim, and Marco Salerno
Review of Corporate Finance Studies, 2024, SSRN version, [+ bibtex]
Dynamic capital structure model
Abstract
We develop a dynamic capital structure model to study how agency conflicts between managers and shareholders affect the joint determination of financing and investment decisions. We show that there are two agency conflicts with opposing effects on a manager’s choice of investment: first, the consumption of private benefits channel leads managers not only to choose a lower optimal leverage, but also to underinvest, and second, compensation linked to firm size may lead managers to overinvest. We fit the model to the data and show that the average firm slightly overinvests, younger CEOs invest more than older ones, while CEOs with longer tenure overinvest more than CEOs with shorter tenure.
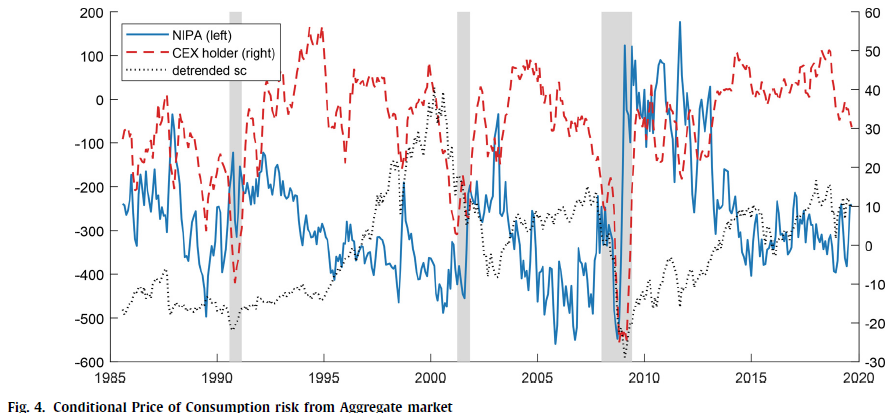
Asset Holders’ Consumption Risk and Tests of Conditional CCAPM
with Redouane Elkamhi
Journal of Financial Economics, 2023, Data and code, SSRN version, Online Appendix, [+ bibtex]
Empirical asset pricing, Asset holders' Consumption, Conditional tests
Abstract
We test the conditional consumption-CAPM using asset holders' consumption and find that the time variation in the prices of asset holders' consumption risk is procyclical. This puzzling time variation is at odds with the implication of existing consumption-based equilibrium asset pricing models. We show that our finding is a salient feature of the data observed in multiple asset classes (aggregate equity market, equity portfolios, bond portfolios, and commodities portfolios), using different measures of consumption (household survey data and high-frequency retail shopping data) and alternative empirical methodologies.Key result
Working Papers
Revise and Resubmit
Does Government Listen to the Public? Measuring Democratic Responsiveness and Its Impact on Business Performance
with Changhyun Ahn, Camilla (Eunyoung) Song, and Joonwoo Yang
Revise and resubmit, Management Science, PUE Data
Presentation: MS Special Issue on Business and Its Interrelationship with Democratic Resilience, Geopolitics, and Society Workshop (2026), Journal of Corporate Finance Conference, “Finance at a Time of Change and Uncertainty” (2026, scheduled)
Measuring Policy Uptake Elasticity and applications to corporate finance
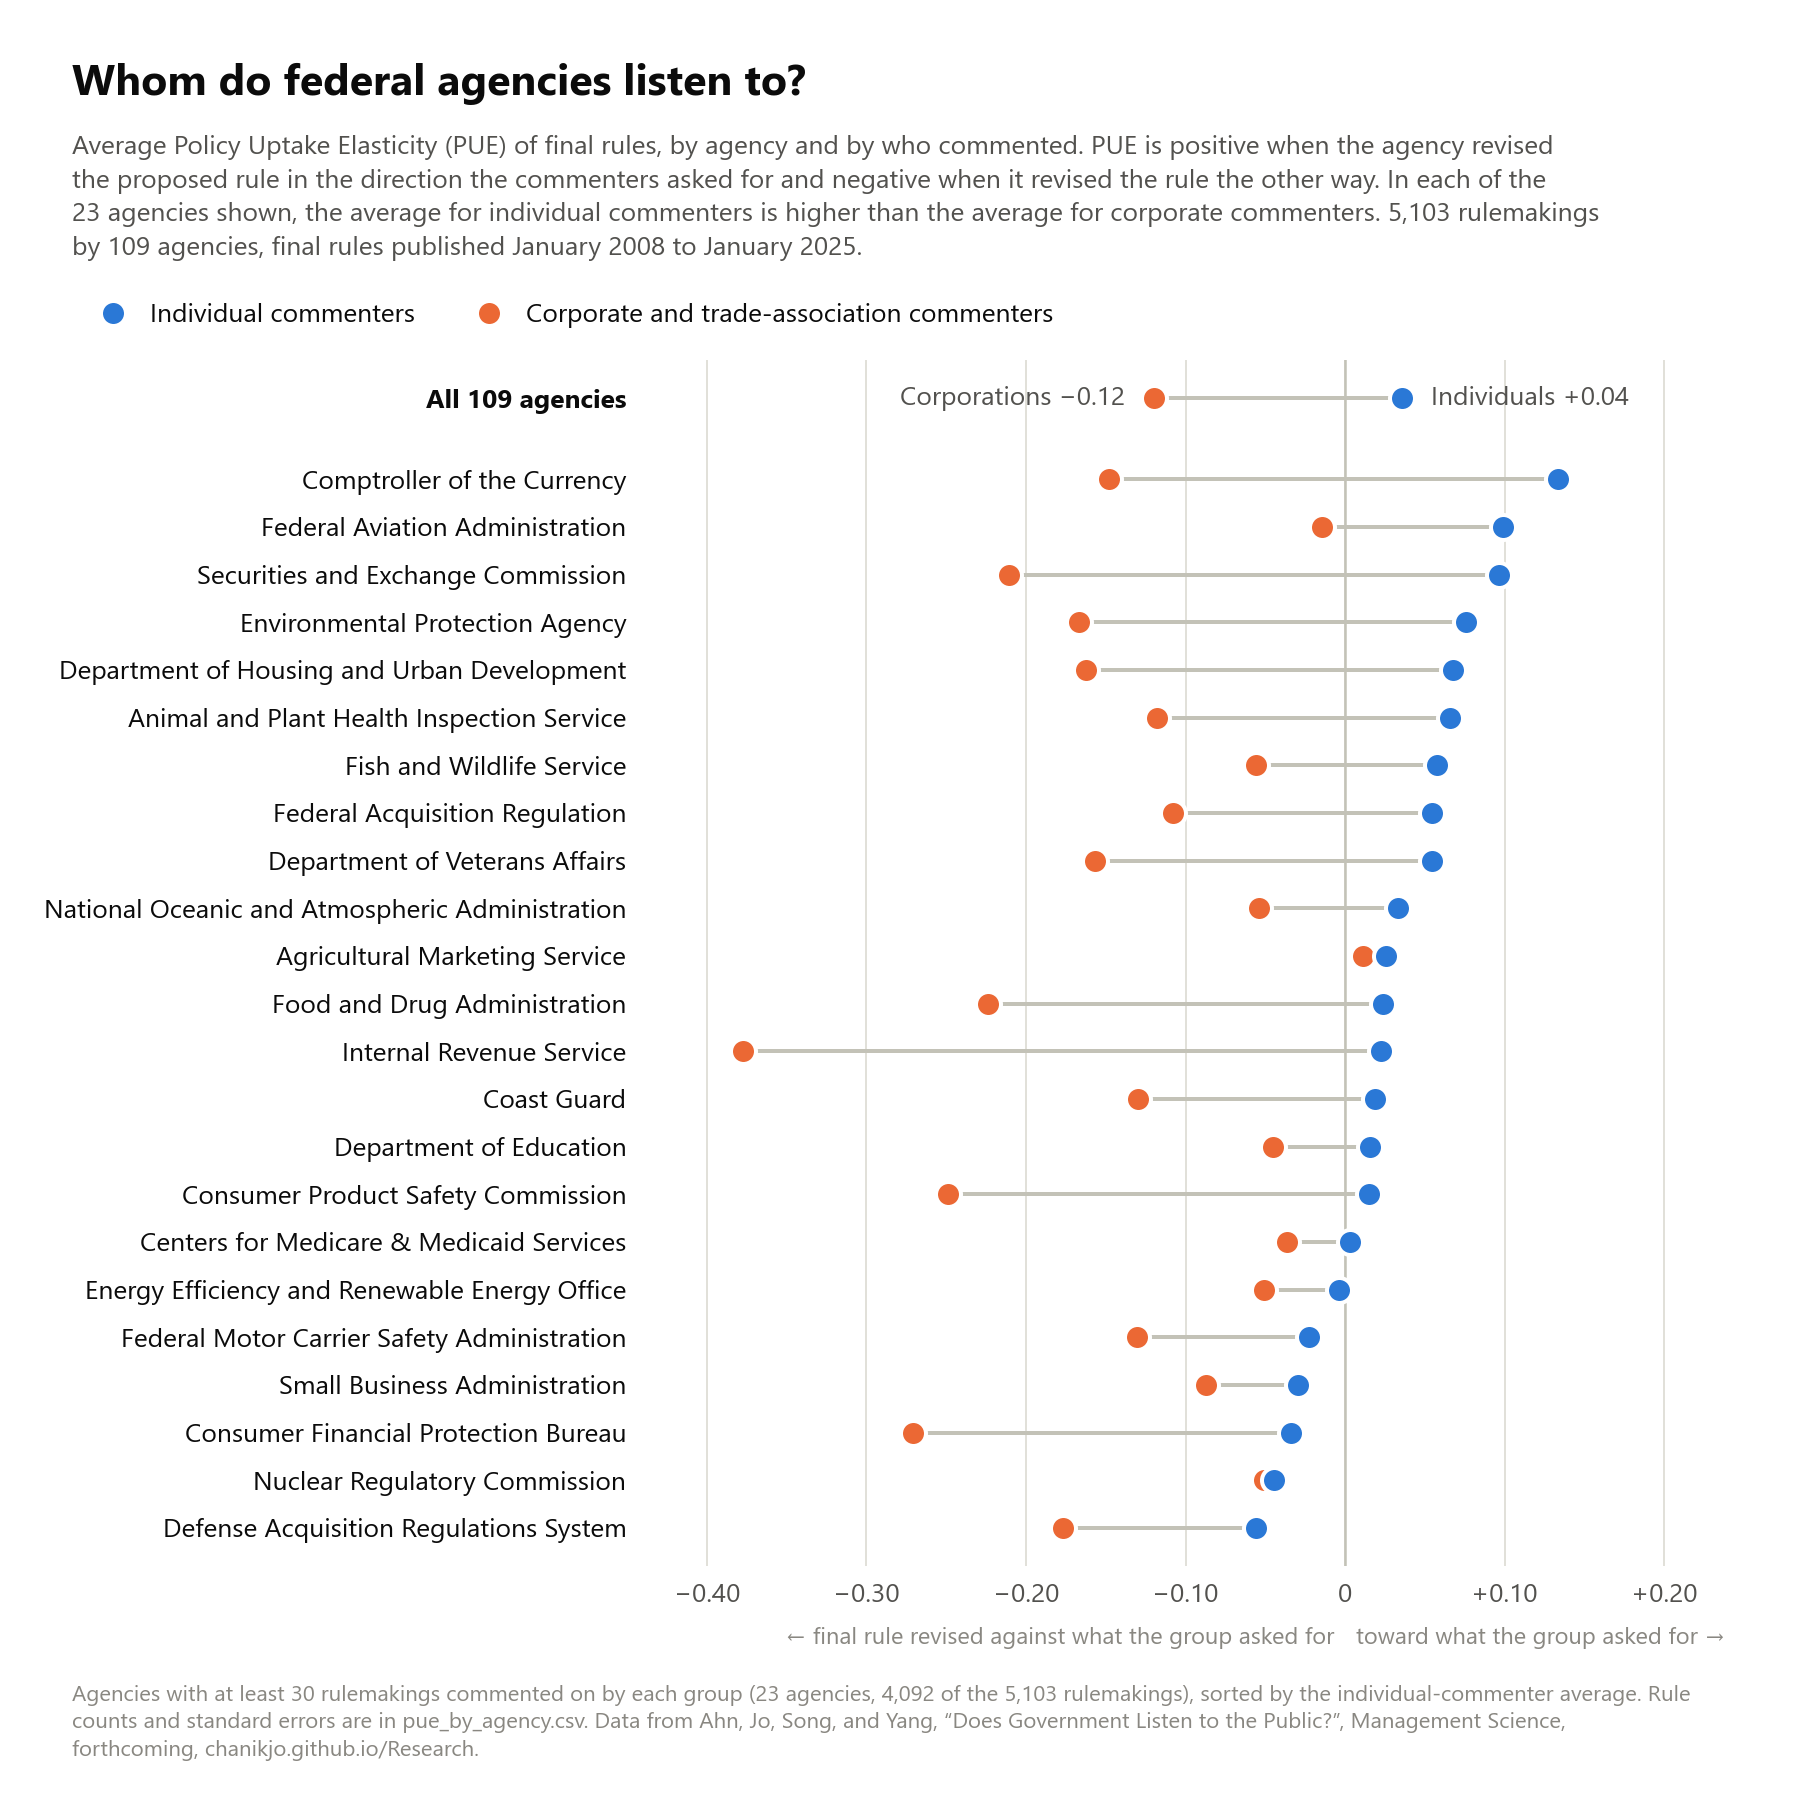
Abstract
This paper introduces Policy Uptake Elasticity (PUE), a measure of agency responsiveness in U.S. notice-and-comment rulemaking. Built from language model classifications of Federal Register rule texts and public comments, PUE measures how much agencies revise proposed regulations toward the position commenters advocate. We validate the classifications against two blind human coders and four other language models. A higher firm-level PUE is associated with lower compliance costs and higher profitability, investment, and sales growth, robust to corrections for classification error and multiple testing. Firms without alternative political access drive the result, consistent with a compliance-cost channel. Responsiveness to individual commenters also declines under acting agency heads, and responsiveness to each commenter group predicts less litigation from that group. Therefore, regulatory responsiveness has measurable relationships with politics, firm performance, and litigation.Key result
Subjective Risk-Return Trade-off
Revise and resubmit, Journal of Banking and Finance
Presentation: MFA (2024), SNU (2023), Korea University (2023), KAIST (2023), Colorado Finance Summit (2022), NUS Risk Management conference (2022), CUHK (2022), Hong Kong Joint Finance Research Workshop (2022)
Media coverage: MarketWatch
Household finance, Subjective expectation, Asset pricing, [+ bibtex]
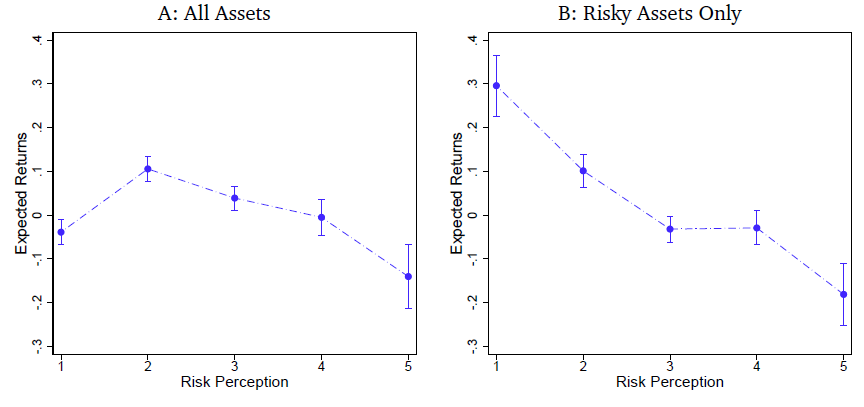
Abstract
We survey 2,548 representative U.S. respondents to estimate subjective risk-return trade-offs across savings, government bonds, stocks, real estate, gold, and cryptocurrencies. We document robust negative relationships between perceptions of risk and return among risky assets, which are observed even among financially literate respondents. Strong asset-specific sentiments, reflected in large deviations of return perceptions from average perceptions, drive these significant negative risk-return trade-offs. Both strong optimism and pessimism contribute to negative risk-return trade-offs with similar magnitudes. These negative risk-return trade-offs translate into under-diversified portfolios, as investors avoid assets they perceive to generate low returns and high risk.Key result
Inflation and Monetary Policy
with Diego García, Michael Shin, and Siyuan Wu
Presentation: AFA (2027, scheduled), MFA (2026), Econometric Society-ASSA (2026), CAFM (2025), FMA (2025), World Congress of the Econometric Society (2025), CU Boulder (2024), KAIST (2024), CUHK (2024), U of Sydney (2024), UTS (2024), Monash Winter Finance (2024), Sydney Macroeconomics Reading Group Workshop (2024), Korea-Japan Finance Workshop (2024)
Inflation, Experience, Attention, and Corporate Finance, [+ bibtex]
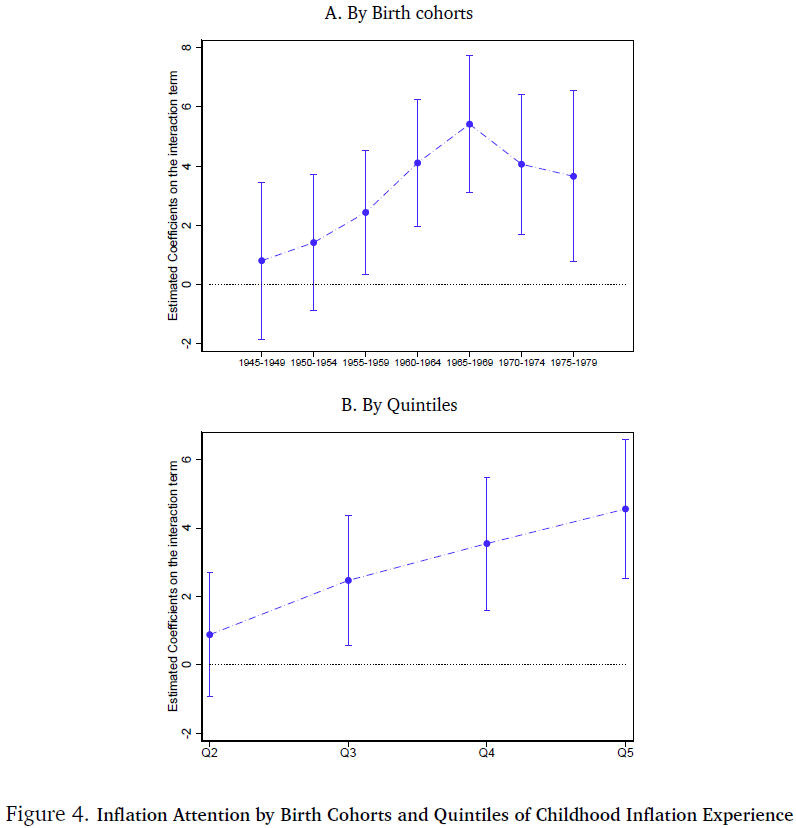
Abstract
We study how firm-level inflation attention influences corporate decisions. We construct a measure of inflation attention, using earnings calls from 2003 to 2024. Our identification strategy exploits exogenous variation in attention from CEOs’ childhood exposure to inflation. We find that CEOs who experience higher inflation in their formative years exhibit greater inflation attention following inflation shocks. Firms led by these CEOs increase leverage, especially fixed-rate debts, reduce cash holdings, and expand employment, consistent with inflation attention reflecting expectations of demand-driven inflation. Our analysis highlights how early-life experiences shape inflation attention and corporate decisions in response to macroeconomic environments.Key result
Is Greenium a Reflection of Core Inflation Risk?
with Zhenyu Gao, Yuyi He, and Yoshio Nozawa
Presentation: UNSW Asset Pricing Workshop (2026, scheduled), SFR (2026), Inaugural KAIST Finance Alumni Conference (2026), Asian FA (2026), Workshop on Climate Risk, Sustainability, and Real Estate (2026), SBFC (2024), LU-JNU Joint Conference for Sustainable Finance and Development in the Digital Era (2024), CUHK (2024), KFA Autumn Conference (2024)
Best Paper Award, Korean Finance Association Autumn Conference (2024)
Greenium, Inflation, and Asset Pricing
Abstract
We present a novel stylized fact that green stocks carry higher inflation risk compared to brown stocks, performing poorly at times of unexpected inflation. Given this fact, can the outperformance of green stocks over brown stocks (the "greenium") be explained as compensation for inflation risk? We find that the magnitude of the greenium decreases by 31% and 54% for Scope 1 and Scope 2, and the greenium becomes statistically insignificant after controlling for individual stocks' core inflation risk exposure. These findings are robust to excluding brown industries and are not driven by the post-COVID inflationary period. Overall, our results suggest that the greenium is in part a reflection of inflation risk compensation.
The Transmission of Monetary Policy to Consumption Through Unemployment Insurance
with Changhyun Ahn, Yutong Yan, and Constantine Yannelis
Presentation: CUHK (2025), CUHK-SZ (2025), Lingnan University (2025)
Monetary Policy, Consumption, Unemployment insurance, Measurement error approach
Abstract
We propose a novel channel through which unemployment insurance (UI) influences the transmission of monetary policy to consumption. Greater UI generosity induces households to lower precautionary savings and invest in stocks, which exposes their portfolios to greater interest rate risk. Consequently, when a monetary tightening shock depresses stock prices, households that previously benefited from expanded UI programs reduce their consumption. To empirically identify this potential channel, we exploit UI measurement errors that are plausibly unrelated to economic fundamentals, combined with a border-county discontinuity approach. Using high-frequency household consumption data and monetary policy shocks, we document that following a UI expansion, contractionary monetary policy shocks reduce household spending within two weeks of FOMC meetings. Our findings underscore unintended macro-financial consequences of UI: while intended to provide income stability, it can inadvertently amplify the adverse effects of monetary tightening shocks through interactions between labor policy and monetary policy.
Do Institutional Investors Use Local Grocery Inflation for Portfolio Choices?
with Byoung Uk Kang and Zhecheng Luo
Presentation: FMA Asia/Pacific (2025), Summer Finance Roundtable (2025), University of Sydney (2025), National Taiwan University (2025), Korea University (2025), CUHK (2023)
Local grocery inflation, Institutional investors, Portfolio choices, Inflation expectations
Abstract
We argue that institutional investors use local grocery price changes as a real-time signal for broader aggregate inflation. Upon observing increases in local grocery prices, they shift portfolios toward high inflation-beta stocks. This behavior is more pronounced among smaller institutions and those with stronger local bias. Some institutions—particularly hedge funds—react differently to local grocery inflation depending on its recent predictive power for aggregate inflation. Their trades also exhibit timing skills, with heightened sensitivity ahead of large impending inflation shocks. While the average institution does not profit from this strategy, hedge funds generate significant subsequent returns, attesting to their ability to exploit local signals effectively.Asset Pricing and Investments
Data Scientists on Wall Street
with Ling Cen, Bing Han, and Yanru Han
Presentation: CICF (2026), ABFER (2026), FinTech and Behavioral Finance Conference (2026), University of Connecticut (2026), City University of Hong Kong (2026), Three Asian Countries Finance Conference (2025), The 3rd Annual Conference on Capital Market Research in the Era of AI (2025), Hong Kong Conference on FinTech, AI & Big Data in Business (2025), PBCSF Tsinghua University (2025), Asian FA (2025), SKKU (2024), Yonsei University (2024)
Institutions, Data Scientists, and Stock Price Informativeness, [+ bibtex]
Abstract
Financial institutions have significantly increased their recruitment of data scientists in the last two decades. We find that the number of data scientists employed by financial institutions causally affects their ability to earn abnormal profits. Data scientists' ability to generate abnormal profits on a stock is positively correlated to the concentration of data scientists across all institutional investors holding the stock. Institutional investors strategically adjust portfolio allocation and recruitment decisions to maximize the benefits generated by their data scientists. Consistent with the notion that the competition among data scientists speeds up the production and trade of private information, we also show that the concentration of data scientists covering a stock reduces its price informativeness in the capital market.
Market Value of U.S. Universities
with Benjamin Bennett, Jaewon Choi, and Yoshio Nozawa
Presentation: CAFM (2026, scheduled), Fixed Income and Financial Institutions (2026, scheduled), Chicago FED/University of Chicago Conference on Municipal Bond Markets (2026), Australian National University (2026), APAD (2026), University of Melbourne (2026), Deakin University (2026), Monash University (2026), NBER Economics of Education (2026), University of Toronto (2026)
Municipal Bonds, Nonprofits, Structural Model of Debt, Merton Model
Abstract
We estimate the market value of “equities” of U.S. private universities by applying a structural credit risk model to the observed credit spreads of their bonds. We find that Yale University is at the top of the ranking, valued at $151 billion, followed by Harvard and Stanford. Should they be listed, their values would be comparable to McDonald's and Intel. Taking advantage of our panel data on the monthly market value of universities, we conduct a difference-in-differences analysis to assess the impact of recent policy changes on university values. The student debt relief announced in March 2020 increased the market value by 17.4%, while the research funding freeze in March 2025 decreased it by 39.4%.
Do Minority Neighborhoods Pay More for Affordable Housing Finance?
with Changhyun Ahn
Presentation: AREUEA-ASSA (2026), CICF (2025), FMA Europe (2025), Fostering Inclusion: A Workshop to Advance Research on Diversity, Equity, and Inclusion at the University of Washington Foster School of Business (2024)
Affordable housing, Multi-family housing, Municipal bonds, Racial disparities, and Racial segregation, [+ bibtex]
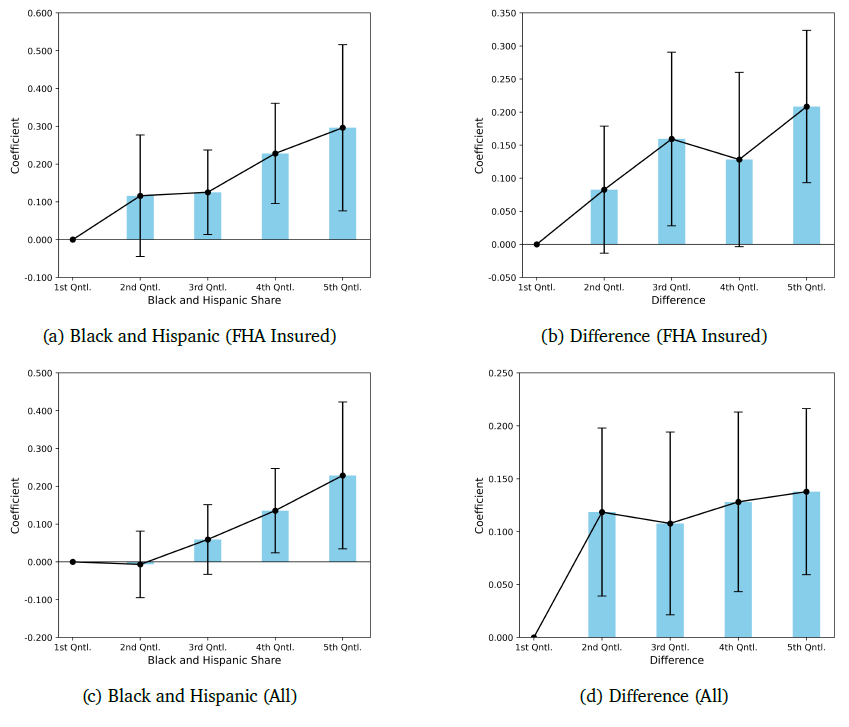
Abstract
State and local governments issue tax-exempt bonds to finance developments of affordable multi-family rental housing. These bonds represent a crucial funding source for addressing the U.S. affordable housing crisis. We find that affordable housing projects in predominantly minority neighborhoods face significantly higher borrowing costs than those in predominantly white neighborhoods. This disparity persists even among FHA-insured bonds where credit risk is essentially eliminated through federal guarantees. The effect is stronger when project neighborhoods have a higher minority concentration compared to surrounding areas, suggesting that financing costs may incentivize development in racially homogeneous communities, potentially reinforcing existing patterns of racial segregation.Key result
Who Bears the Climate Risk? State Guarantees and the Pricing of Physical Hazard in the Municipal Bond Market
with Changhyun Ahn and Yuyi He
Presentation: Sydney Banking and Financial Stability Conference (2026)
Municipal bonds, physical disaster risk, state credit enhancement, school district debt, offering yields
Abstract
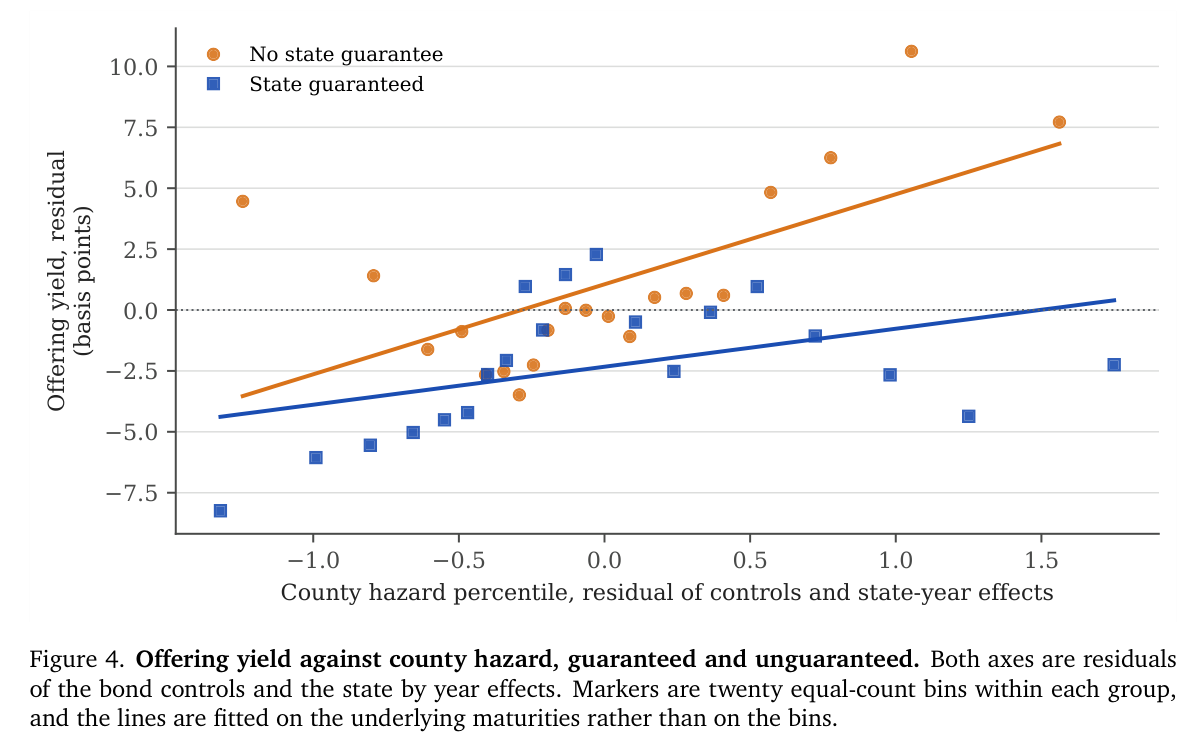
Twenty-two states guarantee school district bonds by statute, replacing district credit with state credit. We ask who pays for physical disaster risk. Across 716,211 uninsured general obligation maturities offered between 2009 and 2022, a standard deviation increase in county hazard raises an unguaranteed issuer's offering yield by 4.58 basis points. By contrast, the same increase changes a guaranteed issuer's yield by less than two basis points. Against unguaranteed school districts alone, the same increase still costs a guaranteed district about one basis point. A statute therefore shifts the bulk of the price of county hazard off the borrower.Key result
The Composition of Market Participants and Asset Dynamics
with Kane Kyuho Bae
New Draft Available Soon
Presentation: SFS Cavalcade (2021), RCFS/RAPS Winter Conference (2020), EFA (2019), CICF (2019), APAD (2019), EFMA (2019), ABFER, CEPR and CUHK (2019), SFS Cavalcade Asia (2018), NFA (2018), FMA (2018), YES (2018), TADC (2018), AFM (2017), AFBC (2017), Indiana University (2017)
Outstanding Paper Award, Joint Conference with the Allied Korea Finance Associations (2023)
Theoretical asset pricing and stock market participation, [+ bibtex]
Abstract
We develop a dynamic equilibrium model where heterogeneous investors endogenously choose to enter/exit the stock market. We characterize the equilibrium and present a conditional consumption CAPM. The model implies small changes in the composition of stockholders, which generate a strongly countercyclical stockholders’ amount of consumption risk. The model provides a new perspective on the main drivers of asset dynamics. It is the procyclical consumption risk-sharing implied by changes in stockholders' composition that contribute to the dynamics of risk premium, excess volatility, and price-dividend ratio. We provide empirical evidence on market participation, amount of risk, and price of risk, supporting our theory.
Beyond Size and Value in China: A Stochastic Discount Factor from Sixty Characteristics
with Kiryoung Lee, Yuyi He, and Gang Li
Stochastic discount factor, Machine learning, Asset pricing, Chinese stock market, Limits to arbitrage
Abstract
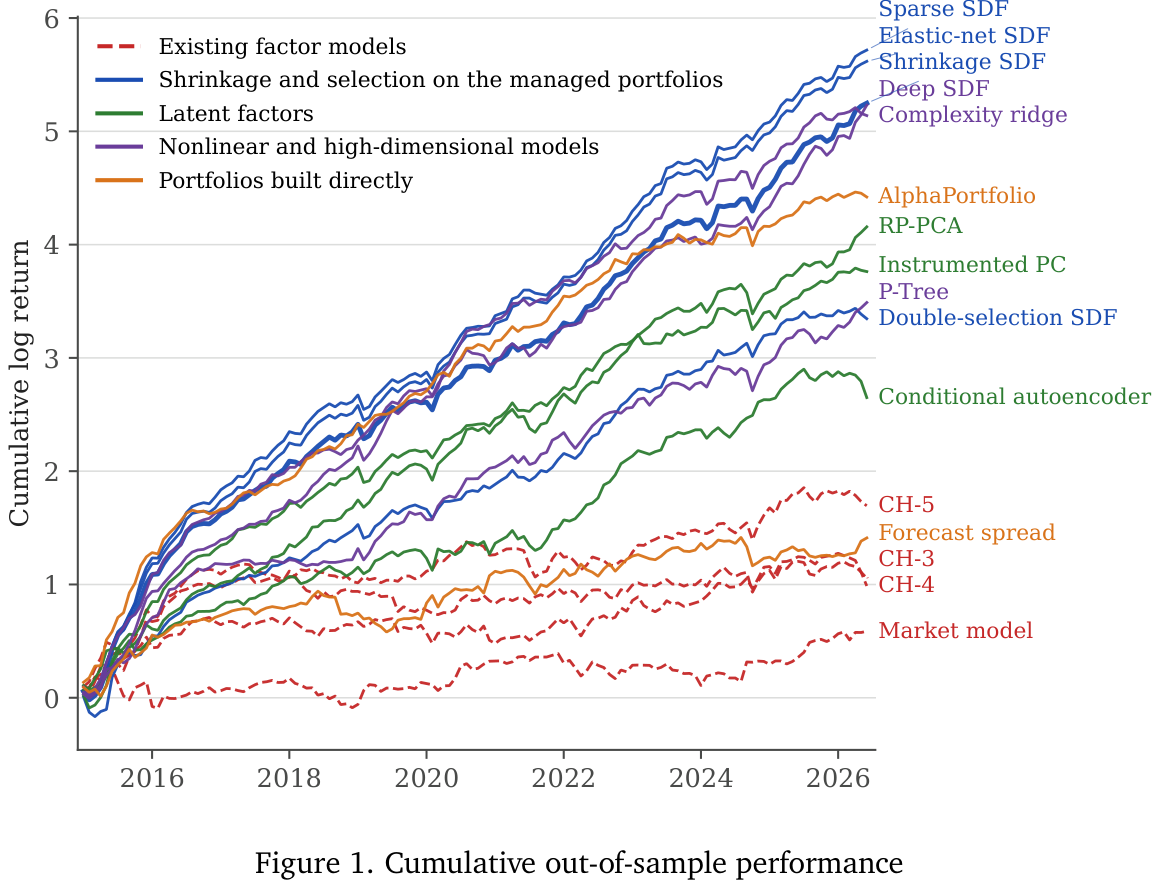
We compare four factor models and 12 machine-learning models for Chinese A shares out of sample from January 2015 to June 2026. Every machine-learning discount factor built on 60 characteristics attains a Sharpe ratio between 1.42 and 3.00, and every factor model between 0.38 and 0.94. The characteristics a model uses therefore decide more than the estimator that combines them. Net of each stock's transaction cost, a discount factor estimated by adversarial networks earns the highest Sharpe ratio, 1.49 against 1.25 for one estimated by shrinkage and 0.14 for the four-factor China model. Liquidity and volatility characteristics, not size and value, produce that performance, and the Sharpe ratio rises as the universe widens to smaller, less liquid stocks, consistent with mispricing that short-sale constraints and arbitrage costs keep in place. Factor models for A shares should therefore include the liquidity and volatility characteristics that the three- and four-factor models omit.Key result
Household Finance
Social Transmission of Consumption
with Zhenyu Gao, Bing Han, and Zhecheng Luo
Presentation: Conference on Social and Behavioral Finance (scheduled, 2026), Chung-Ang University (2026), Asian FA (2026), WFA (2026), York University (2026), PHBS (2026)
Social finance, Consumption, [+ bibtex]
Abstract
We examine whether and how consumption transmits through social networks. Exploiting the U.S. shale boom as an exogenous income shock and county-level Facebook connectedness to identify causal spillovers, we find that 1% increase in a closely connected county's consumption raises the focal county's own consumption by about 0.35% the following year, despite no local income change. The effect is strongest for socially salient and expensive goods, and for more sociable households, consistent with transmission through social observation rather than economic linkages. This peer-induced spending also raises mortgage delinquency rates, weakening household financial stability.
Left-Tail Income Risk and Stock Market Participation: Evidence from U.S. Wrongful Discharge Laws
with Changhyun Ahn and Sing-Sen Lam
Presentation: The 18th NYCU International Finance Conference (2024), Indian School of Business (2024), NTU (2024), FMA Asia/Pacific (2024), Labor and Finance Conference (2023), UNSW (2023), UYSD (2023), UTS (2023), SIPP Virtual Conference (2023), EFA (2020), NFA (2020), MFA (2020), SFA (2020), SWFA (2020), University of Toronto (2020), CUHK (2020)
FMA Asia/Pacific Best Paper Award (Asset pricing/Investment) (2024), Shinhan Bank & KAFA Best Paper Award (2023)
Household finance, Stock market participation, and Labor finance, Online Appendix, [+ bibtex]
Abstract
We exploit the adoption of employment protection laws as a quasi-natural experiment to examine how unconditional left-tail income risk influences stock market participation. Following adoption, participation rises significantly by 7.9% with a dollar holding increase of $1,627. This effect is observed extensively across broad income groups. Conversely, when the laws are reversed, participation declines. Our results are robust to multiple datasets, a stacked difference-in-differences design, and a border discontinuity design. Our calibrated portfolio choice model shows that left-tail income risk alone significantly reduces participation, whereas overall income risk has a material effect only in the absence of left-tail risk.Key result

Climate Change and Households' Risk-Taking
with Zhenyu Gao and Sing-Sen Lam
Presentation: FMA Europe (2025), Finance Down Under (2025), SBFC (2024), CICF (2024), CFRC (2024), SGFIN Annual Research Conference on Sustainability (2024), KAFA-KFMA-KAFE (2023), SIPP Virtual Conference (2023), AFBC (2022), KAFA (2022), CUHK (2022), NTHU Symposium on Sustainable Finance and Economics (2022)
Household finance, Stock market participation, and Climate finance, [+ bibtex]
Abstract
This paper studies a novel channel through which climate risks affect households’ choices of risky asset allocation: a stringent climate change regulation elevates labor income risk for households employed by high-emission industries which in turn discourages households' financial risk-taking. Using staggered adoptions of climate change action plans across states, we find that climate change action plans lead to a reduction in the share of risky assets by 15% for households in high-emission industries. We also find a reduction in risky asset holdings after the stringent EPA regulation. These results are stronger with experiences of climate change-related disasters. Our study implies an unintended consequence of climate regulations for wealth inequality by discouraging low-wealth households' financial risk-taking.
Spouses in The Same Boat: Intra-Household Risk-Sharing and Financial Risk-Taking
with Zhenyu Gao and Sing-Sen Lam
Presentation: UNSW Corporate Finance Workshop (2025), AsianFA (2024), Singapore Rising Scholars Conference (2024), Central University of Finance and Economics (2024), AFA PhD Poster Session (2024), FMA Doctoral Consortium (2023), CUHK (2023)
Best Paper Award, Singapore Rising Scholars Conference (2024)
Household finance, Stock market participation, and Intra-household risk-sharing
Abstract
This paper proposes a novel channel for households' risky asset allocation: better intra-household risk-sharing reduces overall labor income risk for dual-earner couples, thus encouraging households' financial risk-taking. Capturing intra-household risk-sharing dynamics using the conditional income correlation between spouses' industries, we find that better income risk-sharing within couples increases households' financial risk-taking. Exploiting unexpected events of spousal death, we causally identify the impact of intra-household risk-sharing on households' asset choices. Our study implies an unintended consequence of positive assortative mating, a growing tendency of couples choosing partners with similar socioeconomic statuses, which limits risk-sharing between spouses, thereby discouraging financial risk-taking.
Unemployment Insurance and Stock Market Participation
with Changhyun Ahn, Yutong Yan, and Constantine Yannelis
Other Publications
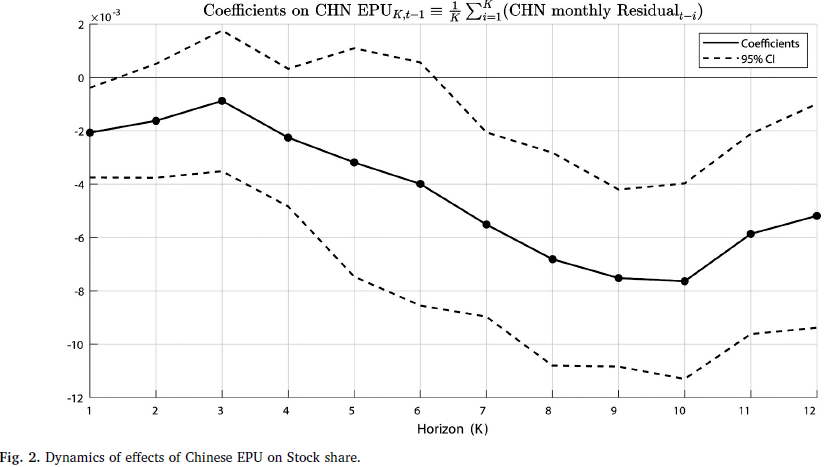
Chinese Economic Policy Uncertainty and U.S. Households' Portfolio Decisions
with Kiryoung Lee and Yoontae Jeon
Pacific-Basin Finance Journal, 2020, [+ bibtex]
Economic Uncertainty, Household Finance, Stock Market Participation, and Chinese Economy
Abstract
We find that U.S. households reduce their exposure to the stock market in response to an increase in the economic policy uncertainty (EPU) of not only U.S., but also to an increase in the Chinese EPU. We identify income uncertainty as a key driver of this relationship. In response to an increase in the Chinese EPU, households whose jobs belong to the industries that heavily export to China react more sensitively by lowering their stock shares in financial wealth. Moreover, the response is stronger for households in states that export to China more than other states. This evidence suggests that U.S. households respond to the Chinese EPU because an increase in the Chinese EPU potentially increases their income uncertainty. Our findings provide the first evidence on the importance of considering foreign economic policy uncertainty in explaining households' portfolio decisions.Key result